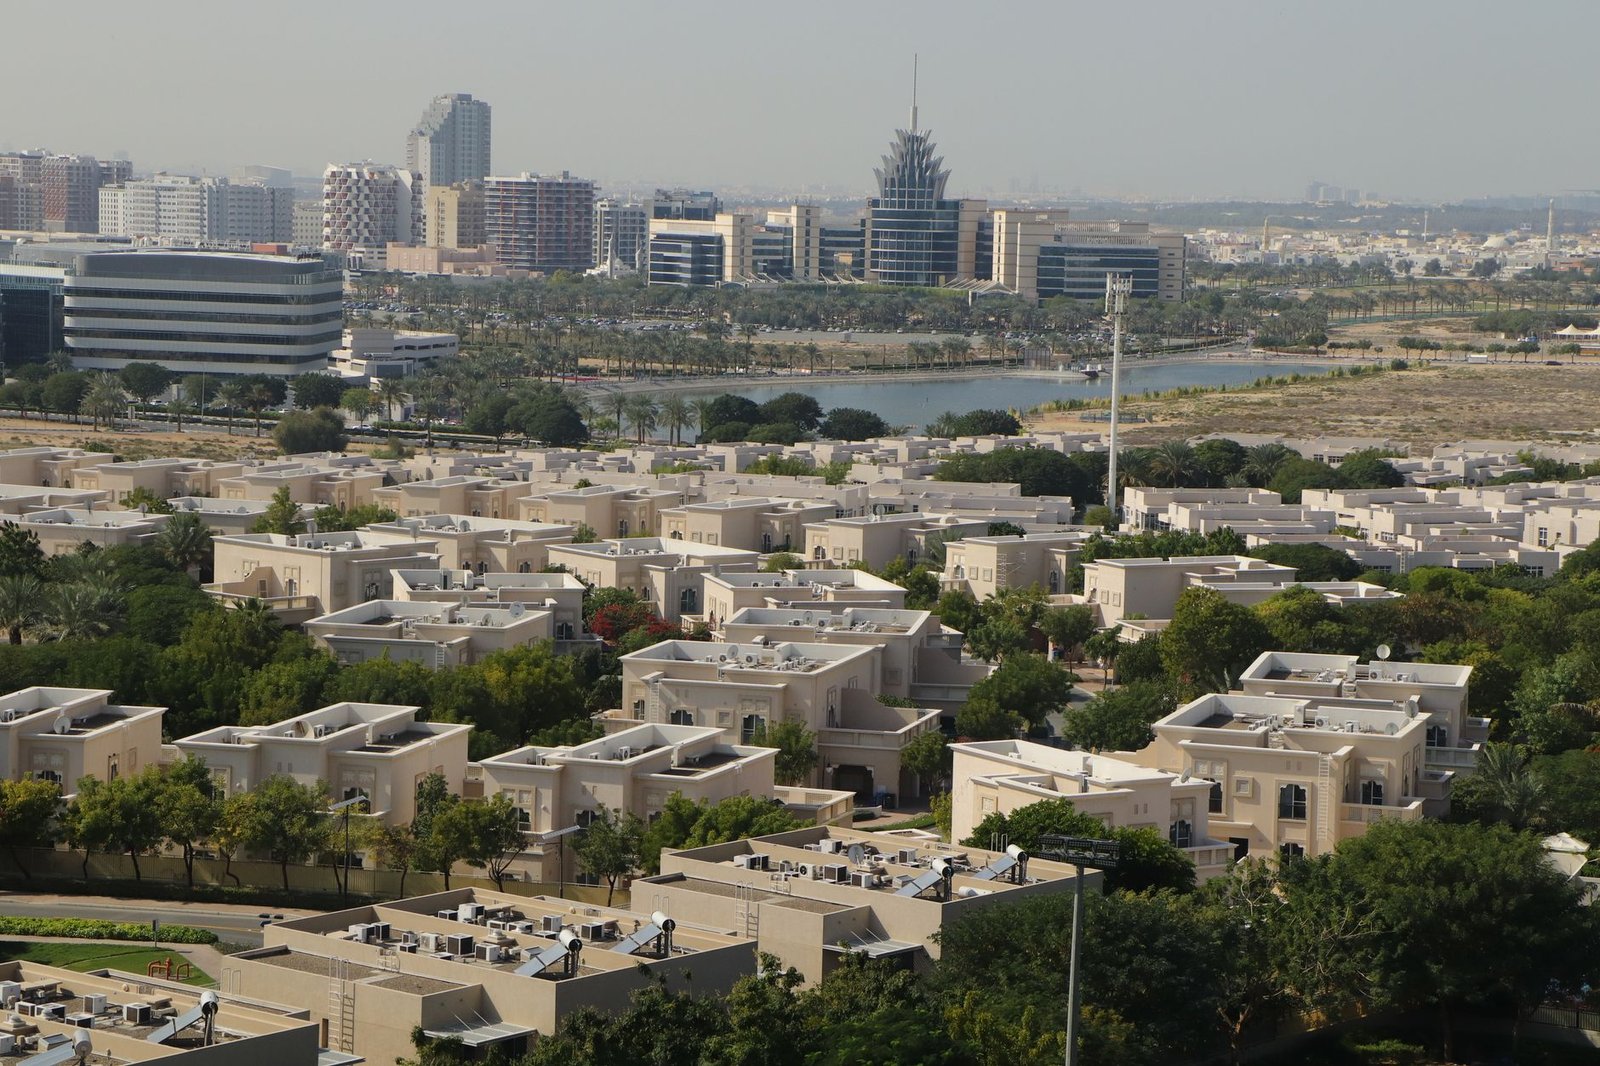
Dubai’s property market spent the last two years dominated by headlines about record-breaking villas and branded residences. That story is changing. Real 2026 data from Savills, developer sales figures, and Dubai Land Department (DLD) transaction records all point the same direction: demand is rotating toward the AED 1 million to AED 2 million bracket, and away from the ultra-luxury end of the market. This guide translates that data into a practical answer for buyers: what’s actually driving the shift, and which established Dubai communities realistically offer entry points in this range in 2026.
Published: 19 September 2026
Direct answer: Dubai’s most realistic “affordable” entry points in 2026 sit in the AED 1 million to AED 2 million bracket, concentrated in established, already-serviced communities including Jumeirah Village Circle (JVC), Dubai South, Arjan, Al Furjan, Dubai Land Residence Complex (DLRC), and Nad Al Sheba — not in new, unproven micro-locations. This shift is being driven by softening ultra-luxury demand (down sharply during 2026’s regional tensions) and rising end-user demand from Dubai’s growing resident population, not by falling prices across the board.
Why the Market Is Shifting Toward Mid-Range Homes
Savills Middle East’s Q2 2026 Dubai Residential Market Report recorded a 19% quarter-on-quarter decline in residential transaction volumes, to 35,884 deals, as buyers became more selective amid rising supply and regional uncertainty. Roughly 27,300 homes were handed over in Q2 2026 alone — the highest quarterly delivery volume in recent years — which is giving buyers more choice and more negotiating power than they had in 2024-2025.
At the same time, the ultra-luxury segment cooled noticeably. Speaking at the International Property Show 2026 (Dubai World Trade Centre, 7-9 September), Azizi Developments Group CEO Farhad Azizi said the one type of product not in demand right now is the very expensive tier — properties priced from AED 10 million to AED 15 million. He confirmed his own company’s sales fell 70% during the regional tensions earlier in 2026, and have since recovered to only around 80% of prior levels. Branded residence transactions across Dubai fell 21% by volume and 47% by value in the first half of 2026, to USD 6.02 billion.
Set against that, Azizi Developments reported its typical investor’s budget has actually risen — from around AED 600,000 to AED 950,000 — with a “significant share” of transactions now falling between AED 1 million and AED 2 million, which the company attributes to stronger appetite for quality homes within the mid-range segment specifically.
This isn’t a market crash story. DLD’s own weekly transaction data for 7-11 September 2026 recorded AED 10.67 billion in total activity, including AED 6.78 billion across 2,931 sales transactions in that five-day window alone — the underlying market is still moving large volumes of money. What’s changed is where that money is going.
The Demand Behind the Shift: Dubai’s Growing Resident Base
The mid-range shift lines up with Dubai’s population growth. Dubai’s resident population has passed the 4 million mark in 2026, with credible estimates pointing to somewhere in the region of 175,000 to 225,000 additional residents for the year — driven overwhelmingly by long-term residents and skilled professionals relocating for work, not short-term or speculative buyers. That’s a meaningfully different demand profile from the investor-led, luxury-focused buying that dominated the post-pandemic years: people moving to Dubai to live and work want homes to actually live in, near their jobs and within a realistic budget — which is exactly the AED 1M-2M bracket Azizi and Savills are both describing.
The rental market backs this up. Freehold rental contracts across Dubai rose 3.79% month-on-month in August 2026 to 39,645 contracts, part of a broader trend of more than 257,000 tenancy contracts registered in the first eight months of the year — up 5.5% year-on-year. One-bedroom units accounted for 41% of all rental agreements, the single largest share by unit type. Strong, growing rental demand at the smaller end of the market is a leading indicator for where end-user buying demand tends to follow next.
Which Dubai Areas Actually Offer Entry Points Under AED 2 Million in 2026
“Affordable” in Dubai doesn’t mean untested or unserviced. The communities below are all established, already built out with schools, retail, and transport links, and Sanaya has published a full investment breakdown on each — read the linked guide for area-specific pricing, yield, and growth detail before deciding.
| Community | Typical unit type in this bracket | What differentiates it |
|---|---|---|
| Jumeirah Village Circle (JVC) | Studios and 1-bedroom apartments | One of Dubai’s highest-volume transaction areas; strong rental demand and liquidity |
| Dubai South | Studios and 1-bedroom apartments | Tied to Al Maktoum International Airport’s ongoing expansion; long-term infrastructure growth story |
| Arjan | Studios and 1-bedroom apartments | Central location near Dubai Miracle Garden, competitive pricing versus similarly-located communities |
| Al Furjan | Studios, with townhouses further up the bracket | Metro-connected via Route 2020 (Al Furjan Metro Station), strong studio yields |
| Dubai Land Residence Complex (DLRC) | Studios and 1-bedroom apartments | One of the lower entry-price points in Dubai for a fully freehold community |
| Nad Al Sheba | 1-bedroom apartments, some townhouses at the top of the bracket | Close to Downtown Dubai and Meydan without Downtown/Meydan pricing |
Note that exact unit pricing within any of these communities moves with the specific building, floor, and finish — the figures and yield data in each linked guide were researched and verified at the time that guide was published, and should be treated as a starting reference point, not a live quote. For a current, specific price on a specific unit, speak directly with a Sanaya agent.
A closer look at each community
Jumeirah Village Circle (JVC) remains one of Dubai’s highest-volume transaction areas by unit count, which matters for buyers in this bracket for a practical reason: high transaction volume means more comparable sales, more active listings to choose from, and generally faster resale liquidity than a thinner market. JVC’s studio and one-bedroom stock spans a wide range of buildings and completion years, so condition and building quality vary more than in a newer, single-developer community — worth inspecting in person rather than buying purely off listing photos.
Dubai South carries a different kind of story: its pricing sits where it does largely because the area is still building out around Al Maktoum International Airport’s long-term expansion. That’s a genuine, government-backed infrastructure catalyst rather than speculative hype, but it also means some parts of the community are still maturing in terms of retail, schools, and day-to-day amenities compared with more established areas on this list. Buyers prioritising rental-ready convenience today should weigh that against buyers comfortable holding for a longer growth horizon.
Arjan benefits from a genuinely central location — close to Dubai Miracle Garden, with reasonable access to Sheikh Zayed Road — at pricing that has stayed competitive relative to similarly-located communities. Because Arjan has seen a steady wave of new mid-rise developments in recent years, buyers should compare completion dates and developer track records across buildings carefully; not every project in the area has delivered on the same timeline.
Al Furjan stands out on connectivity: Route 2020 extended the Dubai Metro directly into the community via Al Furjan Metro Station, which is a meaningful advantage for tenants and buyers who commute without a car. Studios here have historically produced some of the stronger yield figures in this bracket, while townhouses — sitting toward the top of, or just above, the AED 2 million range — offer a family-sized alternative for buyers with a slightly larger budget.
Dubai Land Residence Complex (DLRC) is one of the more genuinely lower-entry-price fully freehold communities in Dubai, which makes it worth a look for buyers whose absolute priority is minimising upfront cash outlay. That lower price point does come with a tradeoff: DLRC is less centrally located than JVC or Al Furjan, so buyers should factor in commute times and weigh rental demand from tenants who specifically want to be further from the city centre.
Nad Al Sheba offers relative proximity to both Downtown Dubai and Meydan without carrying either area’s price tag, which appeals to buyers who want a shorter commute into the city core than the other five communities on this list typically offer. Inventory here skews slightly more toward one-bedroom apartments and, at the very top of the bracket, smaller townhouses, rather than the studio-heavy stock found in JVC or DLRC.
What It Actually Costs to Buy at This Price Point
Buying in the AED 1M-2M bracket carries the same fee structure as any other Dubai purchase — the percentages don’t change with a lower price tag, but the total cash required is naturally smaller. Using an illustrative AED 1.5 million ready (secondary-market) apartment purchase:
| Cost item | Rate | Approximate amount on AED 1.5M |
|---|---|---|
| DLD transfer fee | 4% of property value | AED 60,000 |
| Trustee office registration fee | Fixed, AED 4,000-4,200 | AED 4,000-4,200 |
| Title deed issuance fee | Fixed, AED 250-580 | AED 250-580 |
| Agency commission | 2% of purchase price + 5% VAT | AED 31,500 |
| Mortgage registration fee (if financing) | 0.25% of loan amount + AED 290 | Varies with loan size |
Altogether, buyers typically budget an additional 7-10% on top of the purchase price for total transaction costs on a ready (secondary-market) home — closer to 7-8% for a cash purchase, and 8-10% once mortgage-related fees are included. Off-plan purchases registered under the Oqood system are charged a reduced 2% DLD fee in most cases, which can lower upfront cash needs, though the full 4% fee becomes payable if the unit is resold before handover, and buyers should factor in the developer’s own payment plan schedule separately. Since a 2025 Central Bank directive, none of these transaction costs — DLD fees, agency commission, or admin charges — can be financed through a mortgage; they must be paid upfront in cash. See Sanaya’s full DLD fees and hidden costs breakdown for the complete picture across every price bracket.
Financing an Affordable-Bracket Purchase
Mortgage lending in this bracket works the same way it does across the rest of the Dubai market, with one practical difference worth flagging: at lower loan sizes, fixed fees make up a proportionally larger share of total borrowing cost, so it pays to shop lender rates carefully rather than assume a small loan means small fees. UAE Central Bank mortgage caps currently require expatriate buyers to put down a minimum of 20-25% for a first property under AED 5 million (the exact tier depends on whether it’s a first or subsequent mortgaged property), meaning a cash-purchase alternative — buying outright without financing — remains realistic for many buyers at the AED 1M-2M level in a way it often isn’t at higher price points. Buyers weighing the two options should read Sanaya’s Mortgage vs Cash Purchase guide for a full breakdown of the real numbers either way, since the right choice depends heavily on each buyer’s own liquidity and investment goals rather than a single universal answer.
For buyers assembling the required documentation — proof of income, passport copies, Emirates ID (if resident), and bank statements, among others — Sanaya’s documents checklist guide covers exactly what’s needed before an offer can move forward, whether buying with a mortgage or in cash.
Where This Bracket Sits Relative to the Golden Visa
Dubai’s Golden Visa via real estate investment requires a property investment of at least AED 2 million to qualify — meaning most single purchases in this affordable bracket, on their own, fall just under that threshold. Buyers focused specifically on this segment for Golden Visa eligibility should either look at the upper end of the AED 2M range, or explore whether combining more than one property (the rules allow pooling multiple properties to reach the AED 2M threshold, subject to conditions) gets them there. Full detail on eligibility, the application process, and what property types qualify is covered in Sanaya’s Golden Visa through real estate investment guide. Buyers purchasing purely as end-users or as smaller-scale investors, without a Golden Visa requirement, are not affected by this threshold at all.
Who This Segment Actually Suits
This bracket tends to suit three buyer types most clearly: first-time buyers converting from renting into owning (Dubai’s First-Time Home Buyer Programme is directly relevant here), relocating professionals who want a home rather than an investment vehicle, and investors prioritising rental yield and liquidity over capital-value trophy assets. It suits these buyers less well if the goal is Golden Visa eligibility on a single unit, or exposure to the ultra-prime resale market — those goals are better served by a different price bracket and a different strategy, covered in Sanaya’s broader Dubai Property Market Outlook 2026.
It’s also worth being clear about what this shift is not. Savills frames the broader 2026 market as entering a “more measured phase” and normalising after several exceptional quarters — not a downturn. Luxury demand hasn’t disappeared; it remains genuinely resilient in established prime pockets like Palm Jumeirah, Dubai Hills Estate, and Jumeirah Golf Estates, and the quarter still produced headline deals like a record AED 280 million villa sale on Jumeirah Bay Island. What’s changed is the mix — more of the market’s total activity is now happening in the AED 1M-2M bracket than before, alongside continued (if reduced) luxury activity, not luxury being replaced by affordable housing across the board.
How Sanaya Can Help
Sanaya’s own current listings span a broad range, from rental properties up through multi-million-dirham purchases, and our team tracks live inventory across all six of the communities above daily — pricing on specific units changes too often to publish a live figure in an article. If you’re working to a defined AED 1M-2M budget, a Sanaya agent can walk you through exactly which listings currently fit, in which of these communities, along with realistic timelines and real transaction cost estimates for your specific situation.
Message Sanaya on WhatsApp: +971 50 436 5316
Or reach out through our Contact page to speak with our Dubai or London-based team.
Frequently Asked Questions
What counts as “affordable” real estate in Dubai in 2026?
Based on current market and developer data, the AED 1 million to AED 2 million bracket is where genuine mid-range demand is concentrated in 2026 — not a fixed official definition, but the range multiple 2026 sources (Savills, Azizi Developments) point to as where buyer activity is shifting.
Why is demand shifting away from ultra-luxury properties?
Demand for properties priced from AED 10 million to AED 15 million and above softened through 2026, with one major developer reporting a 70% sales decline during regional tensions earlier in the year, since recovered to around 80% of prior levels. Buyers have become more selective as supply has risen, and end-user, rather than speculative, demand now makes up a larger share of the market.
Is the Dubai property market crashing?
No. Savills describes 2026 as a period of market normalisation after several exceptionally strong quarters, not a broad-based correction. Transaction volumes are moderating and pricing is becoming more fragmented across communities, but overall transaction values, including weekly DLD figures exceeding AED 10 billion in September 2026, remain substantial.
Which Dubai areas offer the best entry points under AED 2 million?
Jumeirah Village Circle (JVC), Dubai South, Arjan, Al Furjan, Dubai Land Residence Complex (DLRC), and Nad Al Sheba are established, fully serviced communities where studio and one-bedroom apartments typically fall within this bracket. See each area’s dedicated guide, linked above, for specific pricing and yield detail.
Do I need AED 2 million to qualify for the Golden Visa through real estate?
Yes, a single-property Golden Visa application requires a minimum property investment of AED 2 million. Buyers can also combine more than one property to reach that threshold under current rules. Most single purchases in the affordable bracket described here fall just under it.
What are the real costs of buying a property around AED 1.5 million in Dubai?
Budget roughly 7-10% on top of the purchase price for total transaction costs on a ready property — the 4% DLD transfer fee is the largest single item, alongside a roughly 2% agency commission plus VAT, and fixed trustee and title deed fees. Off-plan purchases under Oqood registration are typically charged a reduced 2% DLD fee.
Is off-plan or ready property better for a budget around AED 1-2 million?
Both have real advantages in this bracket: off-plan typically has a lower entry cost and a reduced 2% DLD fee, spread across a developer payment plan, while ready property lets you move in or rent out immediately with no construction risk. See Sanaya’s Off-Plan vs Ready Properties guide for a full comparison.
Why is Dubai’s population growth relevant to this price bracket?
Dubai’s resident population passed 4 million in 2026, with an estimated 175,000-225,000 additional residents expected during the year, driven mainly by skilled professionals and long-term residents relocating for work. That group is typically looking for a home to live in on a realistic budget, which is a direct driver of demand in the AED 1M-2M bracket specifically, rather than the investor-led luxury demand that dominated prior years.
Are rental yields better in the affordable bracket than in luxury properties?
Generally yes — smaller, mid-range units in high-demand rental communities tend to produce stronger percentage rental yields than large luxury properties, because rental income scales differently than purchase price. See Sanaya’s Best Areas for Rental Yield guide for area-specific yield data.
Should I buy now or wait for prices to fall further in this bracket?
There’s no verified data indicating prices in the AED 1M-2M bracket are falling — demand is shifting toward this segment, which typically supports pricing rather than pressuring it downward. Waiting for a broad price drop in this specific bracket isn’t supported by current 2026 market data; the better approach is comparing specific listings and communities against your budget and goals with a Sanaya agent.
This article reflects data and figures verified as of 18 September 2026 from Savills Middle East, Dubai Land Department, and reported comments from Azizi Developments’ Group CEO at the International Property Show 2026. Prices and figures in Dubai’s real estate market change frequently — speak with a Sanaya agent for current, listing-specific figures.
If you end up renting out a unit in one of these budget-friendly areas, it helps to know the local paperwork, like Ejari registration in Dubai, which landlords need for a valid tenancy contract.
Since many of these under-AED-2-million areas appeal to investors chasing rental yield, it’s worth understanding how buy-to-let mortgages in the UAE factor in rental income, loan-to-value, and rates.